STRATEGY · OCTOBER 2026 · TAX
Geographic Allocation in a DST Portfolio: Where You Own Matters as Much as What You Own
Two concentration risks live inside every real estate portfolio: asset type and location. A closer look at how regional selection shapes DST performance.
721 Hub · October 27, 2026
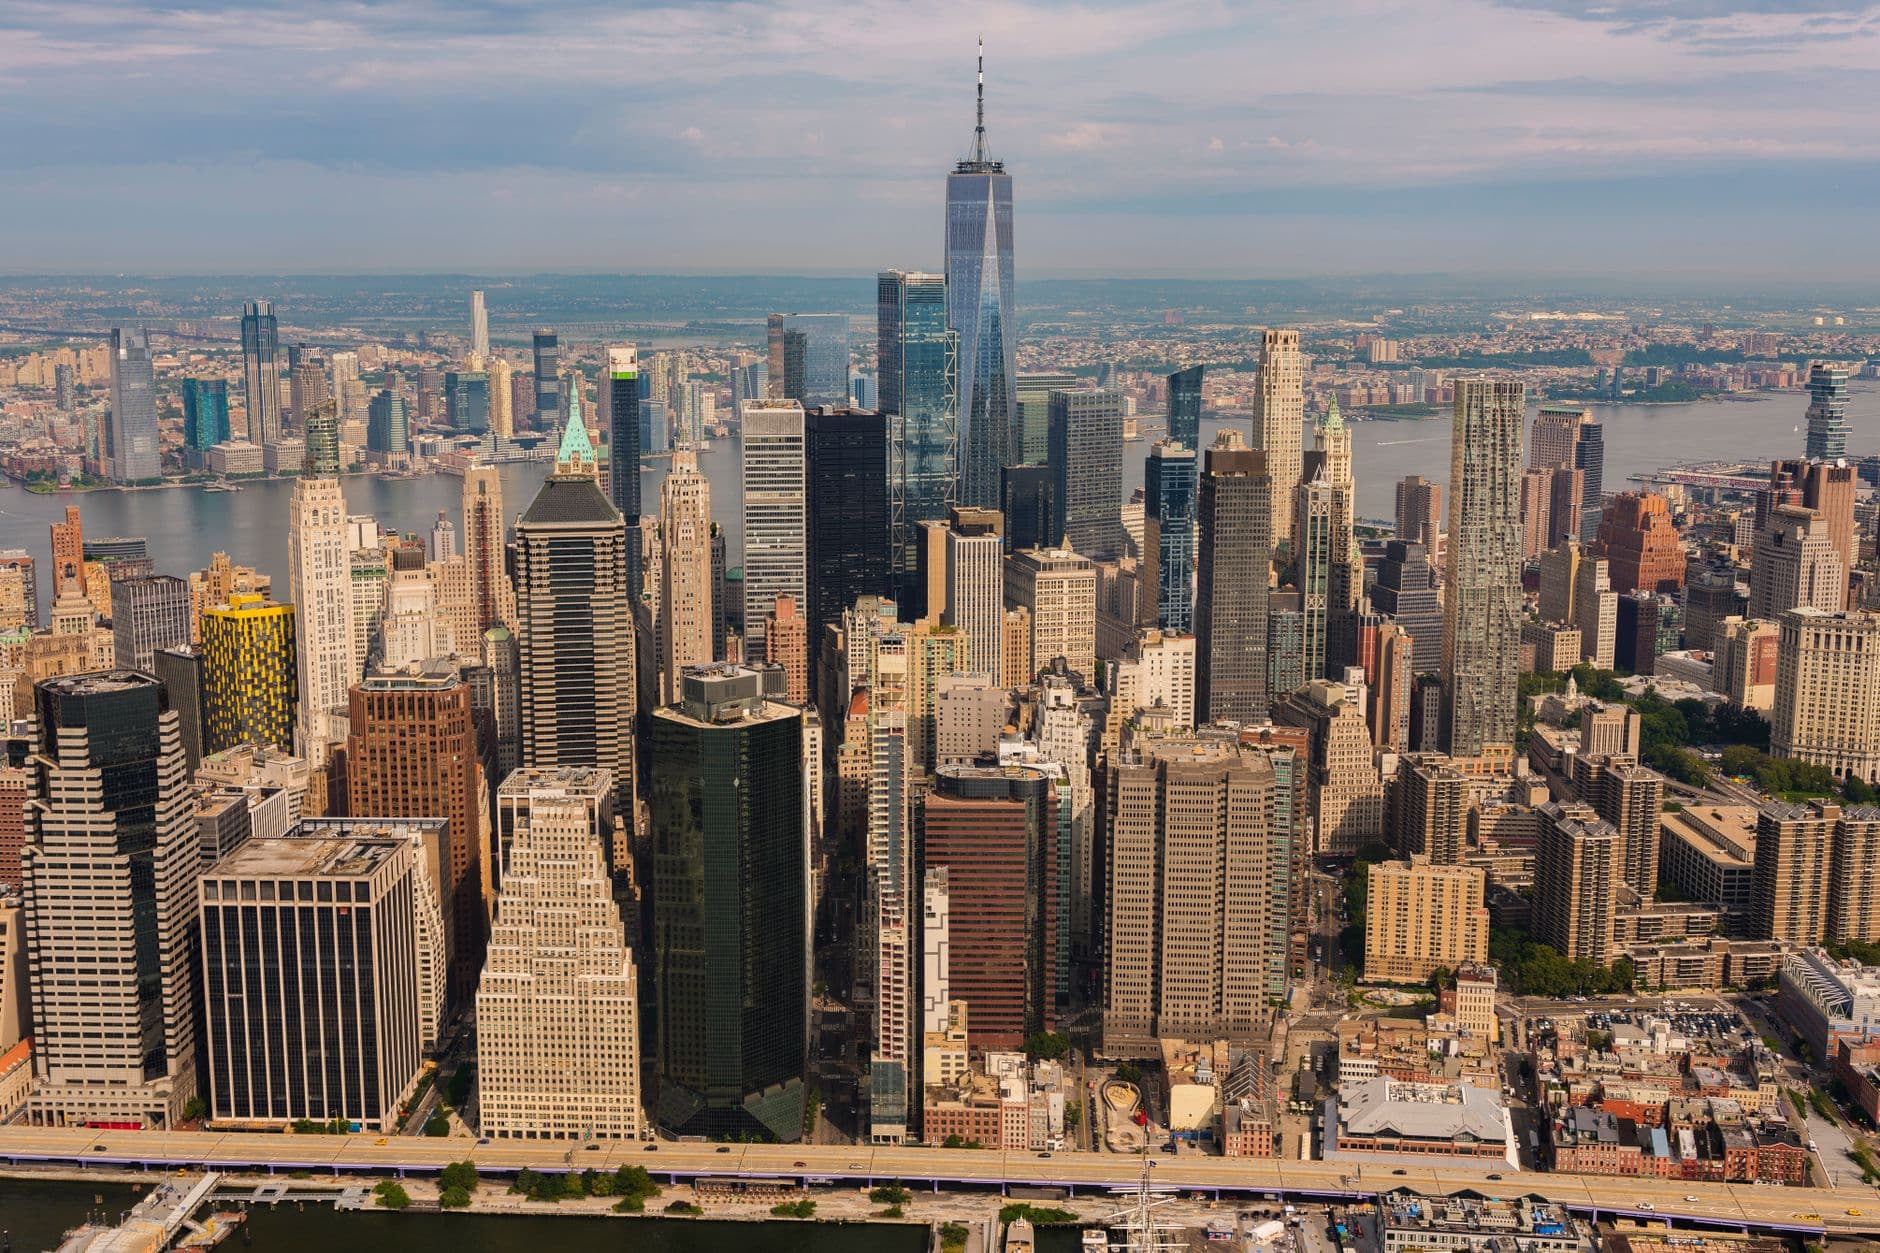
A real estate portfolio carries two distinct concentration risks at once: the kind of property held and the metropolitan area where it sits. Advisors who address only asset-type diversification while leaving geography unconsidered are solving half the problem. Regional selection shapes tenant demand, cap rate behavior, and long-term portfolio resilience in ways that deserve a structured review.
Last reviewed:
The Two-Axis Rule: Asset Type and Geography Together
A portfolio concentrated in one metro, even across multiple asset classes, remains exposed to a single local economic cycle. The defensive posture distributes capital across industrial, multifamily, net-lease retail, medical office, and self-storage, then places those allocations in separate regional markets.
This two-axis framework matters because a slowdown in one city's office sector does not necessarily impair industrial demand in a different region. Investors using Delaware Statutory Trusts benefit from sponsor-level asset management, but the geographic allocation decisions belong to the investor and their advisor at the portfolio construction stage.
A single-market DST sleeve is not inherently problematic. The issue arises when every sleeve points to the same metropolitan statistical area. Concentration at the regional level undermines the diversification rationale that makes multi-asset DST portfolios attractive.
How Location Moves Cap Rates
Capitalization rates are not static metrics. They respond directly to location quality and demand concentration. Prime urban corridors and developed upscale communities tend to carry lower cap rates, reflecting the stability that deep tenant demand pools provide.
Conversely, markets with thinner demand or properties requiring renovation typically price at higher cap rates to compensate for the incremental uncertainty. Neither end of the spectrum is universally superior. An investor prioritizing current income may favor secondary-market assets priced at wider cap rates, while a capital-preservation focus often points toward tighter-cap-rate, high-demand urban assets.
| Location Type | Cap Rate Tendency | Primary Driver | Typical DST Sleeve Role |
|---|---|---|---|
| Prime urban downtown | Lower (compressed) | High tenant demand, limited supply | Stability, capital preservation focus |
| Established suburban corridor | Moderate | Diversified tenant base, stable growth | Balanced income and stability |
| Secondary or value-add market | Higher (expanded) | Thinner demand or renovation need | Income orientation, higher variance |
| SunBelt growth market | Variable by submarket | Population inflows driving demand | Growth-oriented allocation sleeve |
Chicago as a Structural Allocation Target
Chicago presents a case study in metropolitan economic redundancy. The city's tenant demand does not rest on a single industry or employer category. A concentration of Fortune 500 corporate headquarters, a network of major research universities including Northwestern University, the University of Chicago, Loyola University Chicago, DePaul University, Wheaton College, and Columbia College Chicago, and a recognition from PricewaterhouseCoopers as one of a small group of U.S. cities meeting criteria for economic innovation and wellbeing collectively describe a market with layered demand drivers.
For industrial DST sleeves specifically, Chicago ranks among the country's principal distribution hub markets alongside Atlanta, Houston, Reno, Long Beach, and New Jersey. That logistics infrastructure creates durable industrial tenant demand independent of any single sector cycle. Multifamily and office sleeves in the metro benefit from the same diversified employer base that supports the industrial corridor.
SunBelt and Healthcare: Two Demand Themes Reshaping Regional Allocation
An estimated 75 percent of domestic population growth over the coming decade will derive from immigration, with that growth concentrated in Florida, California, and Texas. That concentration has direct consequences for housing, healthcare real estate, and retail tenant demand in those states.
The SunBelt broadly is the primary geography for manufactured housing communities, an alternative real estate sector that follows population density and affordability pressures closely. Florida markets in particular carry the additional structural advantage of no state income tax, which removes a recurring compliance layer for DST investors holding in-state assets.
Healthcare real estate allocation ties directly to demographic geography as well. Medical office buildings represented 58 percent of all healthcare real estate transactions in 2022, and new construction starts for that asset class added nearly 3 million square feet year-over-year in the same period. Advisors building a healthcare DST sleeve should map those construction and transaction patterns against regional demographic concentration rather than treating all markets as equivalent.
- SunBelt metros with high immigration-driven growth: strong multifamily and manufactured housing demand.
- Florida-specific: state tax structure simplifies investor compliance.
- Gateway industrial hubs: Chicago, Atlanta, Houston anchor logistics-oriented DST allocations.
- Healthcare real estate demand follows aging population concentrations, reinforcing Sunbelt and suburban growth-corridor allocations.
Closing Recommendation
Geographic allocation is not a secondary consideration to be resolved after asset-type selection. It is an equal variable in portfolio construction. Advisors should map each DST sleeve against a distinct regional market, stress-test the combined portfolio for single-metro concentration, and confirm that the cap rate environment in each target market aligns with the investor's income versus capital-preservation balance. Accredited investors ready to map their current geographic exposure against available DST offerings should initiate the conversation through the partnered broker-dealer's intake process. Confirm accreditation to proceed.